Using Housing Wealth in Retirement
For homeowners exploring St. Petersburg reverse mortgage options, their home may represent one of their largest retirement assets. A reverse mortgage may provide a way to access a portion of that housing wealth without selling the home or taking on a required monthly principal and interest mortgage payment.
Depending on your age, home value, existing mortgage balance and financial goals, a reverse mortgage may be used to pay off an existing mortgage, establish a line of credit, provide additional liquidity, or help purchase a new primary residence.
The goal isn’t simply to determine whether you qualify. It’s to understand your options and determine whether incorporating housing wealth into your retirement strategy makes sense for you.
St. Petersburg Reverse Mortgage Options
HECM Reverse Mortgage — Age 62+
The FHA-insured Home Equity Conversion Mortgage (HECM) is the most common reverse mortgage and is available to eligible homeowners age 62 and older.
A HECM may allow you to pay off an existing mortgage, access funds as a line of credit or monthly advances, or create additional financial flexibility in retirement.
Proprietary Reverse Mortgage — Age 55+
Proprietary reverse mortgages may be available to eligible homeowners beginning at age 55 and can provide additional options for higher-value homes or situations that may not fit traditional HECM guidelines.
These privately offered reverse mortgage programs can provide different loan amounts, features, and qualification options depending on the homeowner’s situation.
Reverse Mortgage Line of Credit
A reverse mortgage line of credit can provide access to home equity when needed. With an adjustable-rate HECM, the unused portion of the available line of credit grows over time, regardless of changes in the home’s value.
This can provide an additional source of liquidity alongside investments, Social Security and other retirement assets.
Reverse Mortgage for Purchase
Eligible homebuyers can use a reverse mortgage to purchase a new primary residence with a one-time investment at closing and no required monthly principal and interest mortgage payments.
This can be especially useful for retirees relocating to St. Petersburg who want to preserve more of the proceeds from the sale of their previous home rather than using all cash to purchase their next home.
Borrowers remain responsible for property taxes, homeowners insurance, applicable HOA dues, and maintaining the home. The home must be the borrower’s primary residence. Age eligibility for proprietary programs varies by product.
Reverse Mortgages for St. Petersburg Homeowners
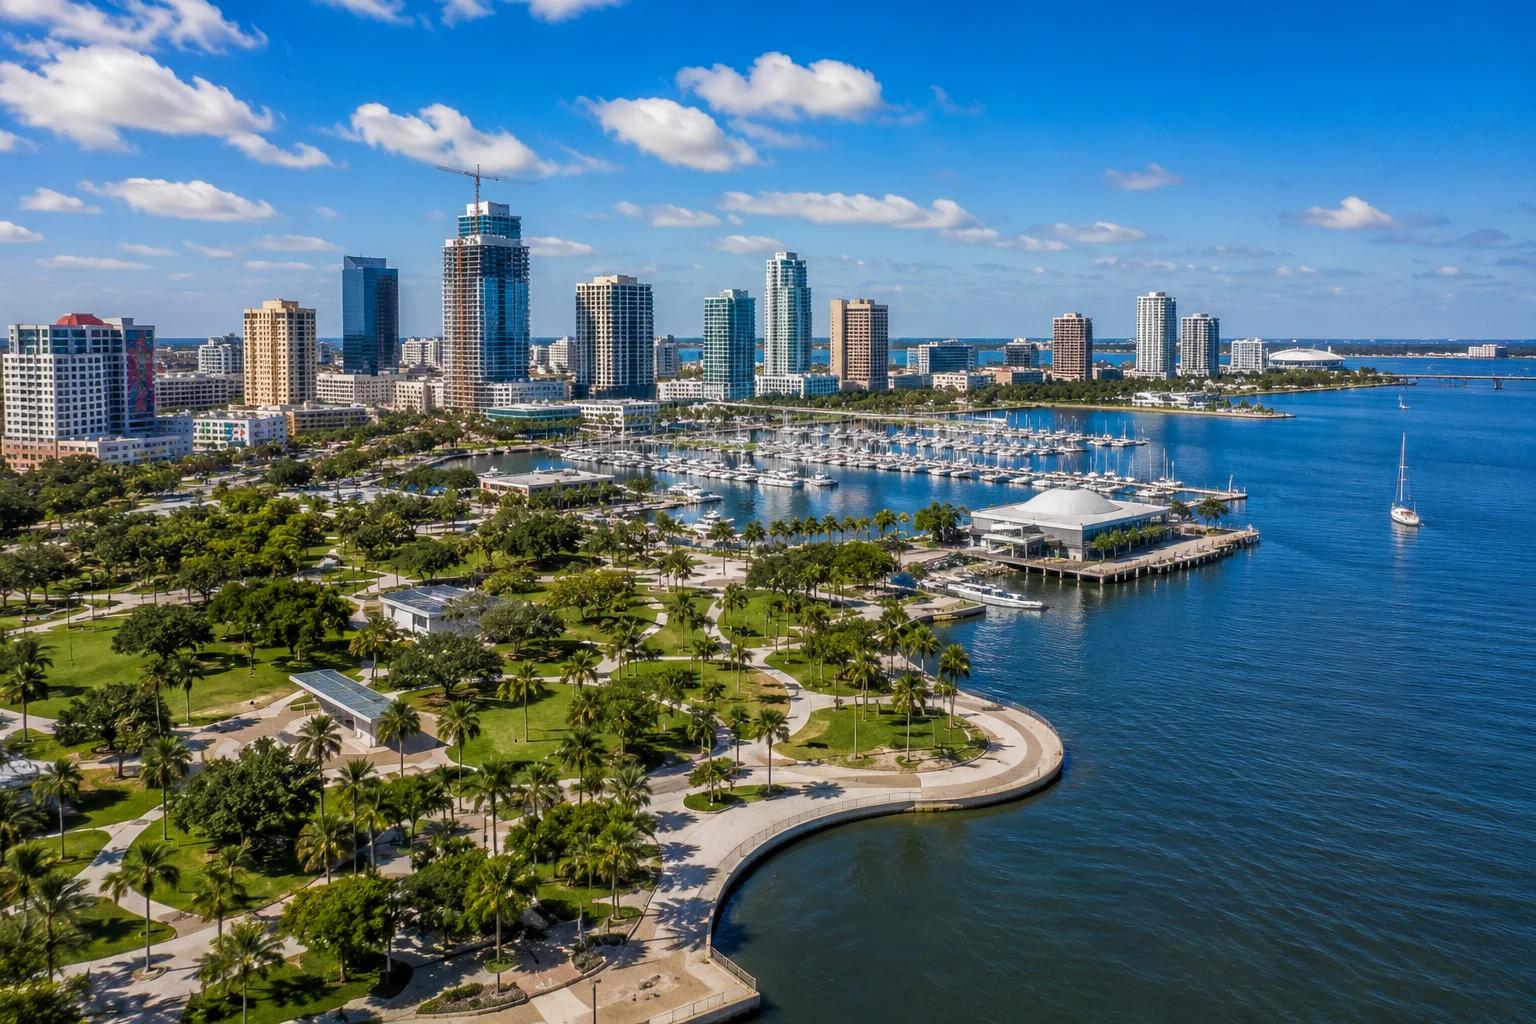
St. Petersburg offers a unique combination of established neighborhoods, waterfront living, active 55+ communities and easy access to everything the Tampa Bay area has to offer.
Whether you’ve owned your St. Petersburg home for decades, recently relocated to the area, or are considering purchasing your next home here, a reverse mortgage may provide another way to incorporate your housing wealth into your retirement plans.
Established St. Petersburg Homeowners
Many longtime St. Petersburg homeowners have accumulated significant equity as their homes have appreciated over the years.
A reverse mortgage may allow eligible homeowners to access a portion of that equity to eliminate an existing mortgage payment, establish a line of credit, create additional liquidity, or address other retirement needs while continuing to own and live in the home.
Retirement Living in St. Petersburg
St. Petersburg and the surrounding Pinellas County area offer a wide variety of housing choices for retirees, including condominiums, single-family homes, waterfront properties and 55+ communities.
Reverse mortgage options may be available to eligible homeowners age 55 and older, depending on the loan program and property type. FHA-insured HECM reverse mortgages are available beginning at age 62, subject to borrower, property, and program requirements.
Serving Homeowners Throughout St. Petersburg
Rick works with homeowners throughout St. Petersburg and the surrounding area, including Downtown St. Petersburg, Northeast St. Petersburg, Snell Isle, Shore Acres, Jungle Prada, Tyrone, Maximo, Greater Pinellas Point and nearby Pinellas County communities.
Looking beyond St. Petersburg? Explore reverse mortgage options throughout the Tampa Bay area.
Considering a Move to St. Petersburg for Retirement?
St. Petersburg has become a popular destination for retirees drawn to Florida’s Gulf Coast lifestyle, warm weather, waterfront setting, cultural attractions and variety of housing options.
If you’re selling a longtime home and relocating to St. Petersburg, paying cash for your next home isn’t your only option. Eligible homebuyers age 62+ may be able to use a HECM for Purchase to buy their new primary residence with a one-time investment at closing and no required monthly principal and interest mortgage payments.
For buyers age 55+, certain proprietary reverse mortgage purchase programs may also be available.
Using a reverse mortgage for purchase may allow you to retain more of the proceeds from the sale of your previous home for investments, reserves, travel, healthcare or other retirement priorities rather than putting all of those funds into your new St. Petersburg home.
Explore Your St. Petersburg Reverse Mortgage Options
Every homeowner’s situation is different. The amount available through a reverse mortgage depends on factors such as your age, home value, existing mortgage balance, interest rates, and the loan program selected.
Whether you currently own a home in St. Petersburg or are considering purchasing one, we can review your situation and provide a personalized comparison of the reverse mortgage options available to you.
Prefer to talk? Call Rick at (702) 460-6222
What Homeowners Are Saying
“I can’t recommend Rick and his team enough! If you are even considering a reverse mortgage product and want the facts, not your neighbor’s opinion, Rick will educate you on the product, no pressure.”
-Maureen M.
“Rick and his staff helped us every step of the way to acquire a reverse mortgage on our property. They respectfully and promptly helped us, giving suggestions and keeping us informed about each stage of the process. I’d recommend Rick to anyone.”
– Greta S.
Common Questions About Reverse Mortgages in St. Petersburg
A reverse mortgage allows eligible homeowners to access a portion of their home equity while continuing to own and live in their home. Unlike a traditional mortgage, a reverse mortgage generally does not require monthly principal and interest payments. The loan typically becomes due when the borrower sells the home, permanently moves out, passes away, or fails to meet loan obligations.
FHA-insured Home Equity Conversion Mortgages (HECMs) are available to eligible homeowners age 62 and older. Certain proprietary reverse mortgage programs may be available beginning at age 55, depending on the lender, property, and program requirements.
Possibly. Condominium eligibility depends on the reverse mortgage program and the property’s approval status. FHA-insured HECMs generally require an FHA-approved condominium project or eligible single-unit approval. Some proprietary programs have different condominium requirements, which may provide additional options.
Yes. Eligible buyers age 62 and older may use a HECM for Purchase to buy a new primary residence with a required investment at closing and no required monthly principal and interest mortgage payments. Certain proprietary reverse mortgage purchase programs may also be available to eligible buyers age 55 and older.
The amount available depends on factors including the youngest applicable borrower’s age, the home’s appraised value, current interest rates, existing mortgage balances, and the reverse mortgage program selected. A personalized loan analysis can help determine which options may be available for your situation.
Yes. With a reverse mortgage, you retain ownership of your home, provided you continue meeting the loan requirements. These include maintaining the property as your primary residence, paying property taxes and homeowners insurance, and keeping the home in good condition. Applicable HOA dues and other property charges must also remain current.
Helpful Reverse Mortgage Resources
Explore additional information about reverse mortgage eligibility, available loan programs, and ways to use home equity in retirement. These resources can help St. Petersburg homeowners and homebuyers better understand their options.