Using Housing Wealth in Retirement
For many Henderson homeowners, their home represents one of their largest retirement assets. A reverse mortgage may provide a way to access a portion of that housing wealth without selling the home or taking on a required monthly principal and interest mortgage payment.
Depending on your age, home value, existing mortgage balance and financial goals, a reverse mortgage may be used to pay off an existing mortgage, establish a line of credit, provide additional liquidity, or help purchase a new primary residence.
The goal isn’t simply to determine whether you qualify. It’s to understand your options and determine whether incorporating housing wealth into your retirement strategy makes sense for you.
Why Henderson Is a Popular Place to Retire
Founded in 1941 as a wartime magnesium town and incorporated as a city in 1953, Henderson has grown into Nevada’s second-largest city — and one of the most popular retirement destinations in the Las Vegas Valley. Here’s what draws homeowners 55 and older to Henderson:
No state income tax. Nevada does not tax retirement income, Social Security benefits, or pension income. For retirees, that means more of your income stays in your pocket — and reverse mortgage proceeds are generally not considered taxable income either.
Year-round sunshine. Henderson enjoys roughly 300 days of sunshine a year, with mild winters that make it easy to stay active outdoors throughout retirement.
Close to Las Vegas, without living in it. Henderson sits about 15 miles southeast of the Las Vegas Strip — close enough for world-class dining, entertainment, and McCarran International Airport, but with a quieter, more residential feel.
Master-planned communities. Henderson is known for its well-planned neighborhoods, including several age-restricted 55+ communities like Sun City Anthem and Sun City MacDonald Ranch, as well as the lakeside setting of Lake Las Vegas.
A reputation for safety. Henderson is consistently ranked among the safest large cities in America, a factor many retirees weigh heavily when choosing where to settle.
Reverse Mortgage Options for Henderson Homeowners
HECM Reverse Mortgage — Age 62+
The FHA-insured Home Equity Conversion Mortgage (HECM) is the most common reverse mortgage and is available to eligible homeowners age 62 and older.
A HECM may allow you to pay off an existing mortgage, access funds as a line of credit or monthly advances, or create additional financial flexibility in retirement.
Proprietary Reverse Mortgage — Age 55+
Proprietary reverse mortgages may be available to eligible homeowners beginning at age 55 and can provide additional options for higher-value homes or situations that may not fit traditional HECM guidelines.
These privately insured programs can offer different loan amounts, features and qualification options depending on the homeowner’s situation.
Reverse Mortgage Line of Credit
A reverse mortgage line of credit can provide access to home equity when needed. With an adjustable-rate HECM, the unused portion of the available line of credit grows over time, regardless of changes in the home’s value.
This can provide an additional source of liquidity alongside investments, Social Security and other retirement assets.
Reverse Mortgage for Purchase
Eligible homebuyers can use a reverse mortgage to purchase a new primary residence with a one-time investment at closing and no required monthly principal and interest mortgage payments.
This can be especially useful for retirees relocating to Henderson who want to preserve more of the proceeds from the sale of their previous home rather than using all cash to purchase their next home.
Borrowers remain responsible for property taxes, homeowners insurance, applicable HOA dues, and maintaining the home. The home must be the borrower’s primary residence. Age eligibility for proprietary programs varies by product.
Reverse Mortgages in Henderson’s 55+ Communities
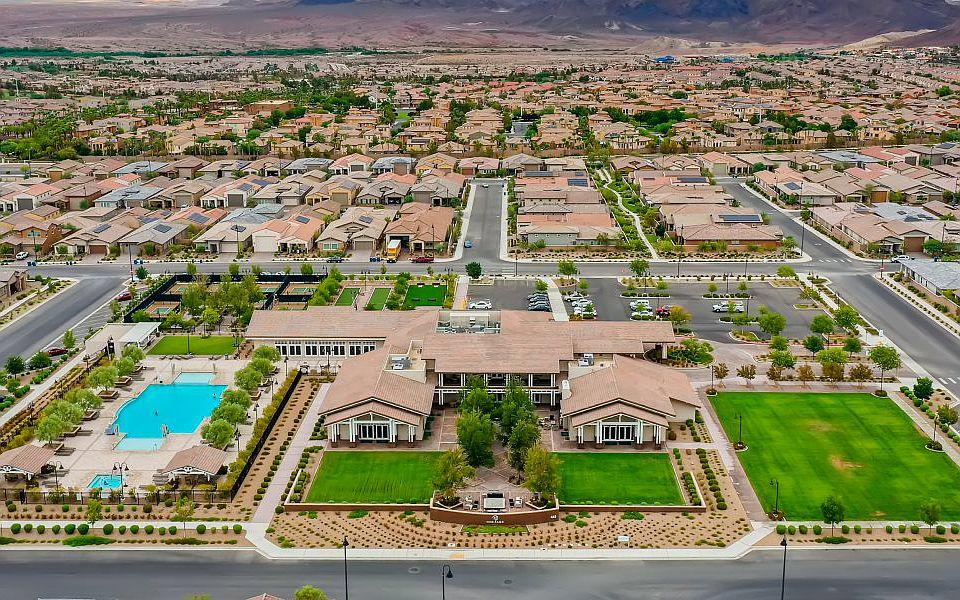
Henderson is home to a number of 55+ and active-adult communities where housing wealth can play an important role in retirement planning. Whether you already live in Henderson or are considering moving here, a reverse mortgage may provide options for accessing home equity or purchasing your next primary residence.
Sun City Anthem
Sun City Anthem is one of Henderson’s largest and best-known 55+ communities. Homeowners may explore a reverse mortgage to eliminate an existing mortgage payment, establish access to additional funds, or use housing wealth as part of their overall retirement strategy.
Sun City MacDonald Ranch
Sun City MacDonald Ranch is an established 55+ community in Henderson offering single-story homes and an active-adult lifestyle. Reverse mortgage options may be available to existing homeowners as well as eligible buyers looking to purchase a primary residence in the community.
Serving Homeowners Throughout Henderson
You don’t need to live in a designated 55+ community to qualify for a reverse mortgage. Rick works with homeowners throughout Henderson, including Green Valley, Green Valley Ranch, Anthem, Inspirada, Seven Hills, Lake Las Vegas, MacDonald Highlands, Cadence, Whitney Ranch and surrounding neighborhoods.
Moving to Henderson for Retirement?
Henderson continues to attract retirees who are looking for an active lifestyle, desirable communities and the advantages of living in Southern Nevada.
If you’re selling a longtime home and moving to Henderson, paying cash for your next home isn’t your only option. Eligible homebuyers age 62+ may be able to use a HECM for Purchase to buy their new primary residence with a one-time investment at closing and no required monthly principal and interest mortgage payments.
For buyers age 55+, certain proprietary reverse mortgage purchase programs may also be available.
Using a reverse mortgage for purchase can allow you to retain more of the proceeds from the sale of your previous home for investments, reserves, travel, healthcare or other retirement priorities rather than putting all of those funds into the new home.
Explore Your Henderson Reverse Mortgage Options
Every homeowner’s situation is different. The amount available from a reverse mortgage depends on factors including your age, home value, existing mortgage balance, interest rates and the reverse mortgage program you choose.
Whether you currently live in Henderson or are considering purchasing a home here, I can prepare a personalized analysis showing the options that may be available to you.
Henderson Reverse Mortgage FAQs
Yes. A HECM for Purchase allows eligible buyers age 62 and older to buy a home in Henderson using a reverse mortgage, combining a down payment with reverse mortgage proceeds. This is popular with retirees relocating to Henderson’s 55+ communities who want to preserve cash rather than paying all cash for their next home.
Generally, yes. Most 55+ communities in Henderson, including Sun City Anthem and Sun City MacDonald Ranch, do not restrict reverse mortgages. However, HOA dues must be factored into the qualification, and the borrower remains responsible for paying HOA dues, property taxes, and homeowners insurance throughout the life of the loan.
Nevada has no state income tax, which means retirement income, Social Security, and pension income are not taxed at the state level. Reverse mortgage proceeds are generally not considered taxable income at the federal level either, since they are loan proceeds rather than income. This combination makes Henderson particularly attractive for retirees managing cash flow. Consult a tax advisor for your specific situation.
It depends on the property. FHA-approved condos may qualify for a HECM, while proprietary reverse mortgages may offer more flexibility for non-FHA-approved condos and townhomes. We can review your specific Henderson property to determine which programs it qualifies for.
A reverse mortgage refinance may allow you to access your home equity while staying in your Henderson home. Options include a lump sum, a line of credit that grows over time, or monthly payments — all without a required monthly principal and interest mortgage payment, as long as you meet the loan obligations.
Yes. You retain ownership of your home, just as with a traditional mortgage. The loan typically becomes due when the home is sold, the last borrower permanently moves out, or the last borrower passes away. The loan is non-recourse, meaning you or your heirs will never owe more than the home is worth at the time of repayment.
Helpful Reverse Mortgage Resources
Explore additional information about reverse mortgage eligibility, available loan programs, and ways to use home equity in retirement. These resources can help Henderson homeowners and homebuyers better understand their options.